Showing posts with label YOD. Show all posts

Tuesday, April 28, 2015

April 28

I had planned to be completely out of the market but sometime money is just gift wrapped for you.  

YOD was up this morning as it gapped up over 20% on news that its Video service would be on trains in China. There is no need to go into the specifics here but based on my prior research I understood who would be pumping this move and that it would not lead  to lasting moves or a break away gap.   So I went short.

  2.72 and 2.61  YOD ultimately collapsed and I covered at $2.20 


Saturday, November 8, 2014

Closed YOD short

I closed my YOD short at 2.86.-- from my 2.97.  Another winner on YOD (I'm now 6 for 6 on my YOD short sales).  This is not one to boast about as I was unable to get any size on the trade. I attempted to borrow shares throughout Thursday and Friday but to no avail. To that end, this trade stopped being worth my time as there are better opportunities.  

That being said, If a block of shares were to free up, that gap fill still looks tasty. 


Thursday, November 6, 2014

Opened Short: YOD

I shorted YOD yesterday at 2.97.  My hypothesis on this trade is that the move has now aged and momentum is leaving.  That gap should fill.  That being said, I drew the fib lines on the day 1 breakout.  Very Interesting.  The pull back day pulled right to the 23.6.  Yesterdays move ran to the 161 and the pull back stopped at the 100.  Coincidence?  


Monday, November 3, 2014

Closed: TUBE, YOD, Day trade BABA

Today was kind of a a "meh day."  I didn't get much traction on anything.  I closed 3 positions for a total of 1R profit.

First Tube.   This was just a disappointing trade as it had potential but faded once it looked it would gain traction.  I really dislike b/o faders.  So I banged it out.  This needs to set up as a flag again and I would bet that it is going to take 15-20 days before it is ready to breakout.

Trade Summary
Entry: 15.09
Exit: 15.43
+ .26R

My entry was relatively poor in this stock as an entry at 14.80 should have been had.  But what ever, this is what it is.


YOD:
On the Short side my fade of YOD played out perfectly.  I bought it in as the volume started to dry up.  I had set a buy order at 1.86 last night--turned out to be the LOD.  That being said, so did some other traders and I didn't get filled there I got filled.  I banged it out at $1.94

Entry: 2.19 avg
Exit: 1.94
.58R

This one worked out well.  No need to be a hero or wait for another .20.
BABA:
Baba set up for a nice breakout. 101.20.  It made a nice run after word hitting a high of 102.80.  I am very adverse to b/o fades and I hate taking a loss after I'm up over a pt in a stock so I moved my stop to 101.75.  Although that held for most of the day a late day plunge took me out -- filled at 101.77
Trade summary
Entry 101.20
Exit: 101.77
.18R  BABA then decided to surge on A.H. trading as traders wanted to get in before earnings.  I thought I saw a 105 print which would have been good for at least 3R from my entry.  Oh well--protect capital first.


Saturday, November 1, 2014

Opened YOD short

YOD got a fantastic pop on rumors that BABA was interested in purchasing it via "unconfirmed market chatter." As with most stocks that pop due to buyout rumors  I have little doubt that YOD will fade completely.

I've have a very good handle on YOD.  I have traded this stock a number of times during the past year and recognize the absurdity of such a rumor.  In addition to YOD's wide spread insider dilution via warrant exercise the economics of a YOD / Baba deal simply do not make sense. BABA already owns 16% of yoku and just launched as a new platform to market YOKU's videos.  So what would buy an American company with non-exclusive licenses to compete with its partner?  That won't happen.  Despite what the pumpers on twitter were saying.

Eventually the momo traders came to their senses and started to fade this stock. Enter my short opportunity:

Entry 1: 2.39
Entry 2:  209
Avg. 2.19
Risk: 1.5R


A very long wick on that daily candle which suggests that this will not be a multi-day pop. This was  a 1 and done type move, imo.  Given the speed and volume on the  sell off I increased my position by 2/3 going into the close. 


Under normal circumstances,  I would target 1.85-1.95 range and I'll probably partially cover in that range.  I suspect, however, that due to the volume there will be some new bag holders that are now trapped.  I very much doubt anyone bought this as a long term hold as the fundamentals are unproven and have underperformed for years.

2 years ago Analyst forecasted revs of over 20 mill-- not even close, Last year $15  mill. nope.  Early this year $9 mill.  The company now says $3 mill.  As pathetic is that is for a company that claims as an 11 million viewer market, the company has earned less than 200k in both Q1 and Q2.   I'll  target 1.65- 1.55 within a few days as rally attempts fail When the reason for the buying spree has evaporated, stocks tend to over-adjust the other way so this has the potential to go even lower near term.

Tuesday, July 8, 2014

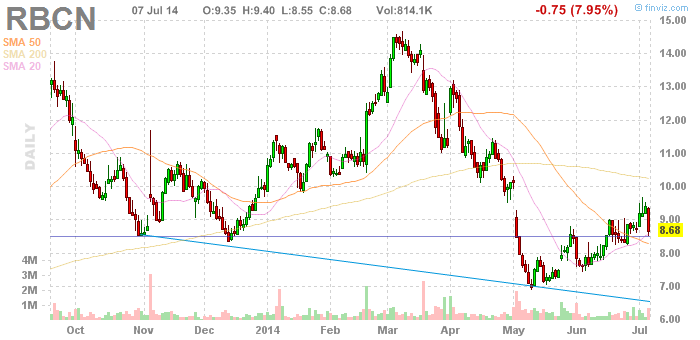
Closed Positions. RBCN, YOD

I closed my remaining half on the break of 9.   The catalyst behind the sell-off was down grades to sector leader Gtat, which was down over 3.00.  I knew RBCN wouldn't be saved from the selling so I decided to save more profits.  (9 had been resistance, resistance becomes support and support was broken.  All in all a very good trade for me.  In at 7.52 out at 8.92 (on this portion of the trade.  Some profits were taken as high as 9.29.


YOD:

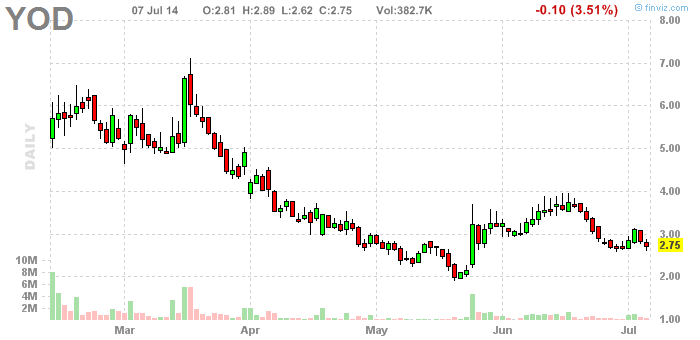
I finally closed my short of YOD avg $3.44  bought in  @ 2.75 (avg)  I  was only going to close 1/3 of my position, but in all honesty I just go bored with it as volatility and volume have completely dried up.    I exit with a decent  profit on the trade.


Tuesday, May 27, 2014

Current position summary.

Longs:

SFUN  Looking very nice.  Bought at 11.23 average.
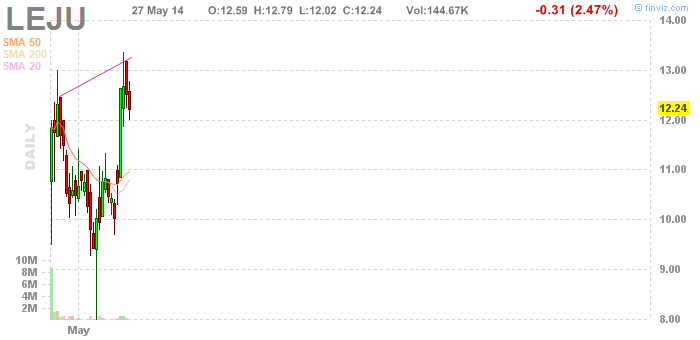
Leju: Bought at 10.65.  The recent Ipo trading history is short but it has come back with a vengeance after an IPO flop? It great earnings and pickup 3 more analysts all with buy ratings.  Ideally, I would like to see consolidation and the 12 hold.  

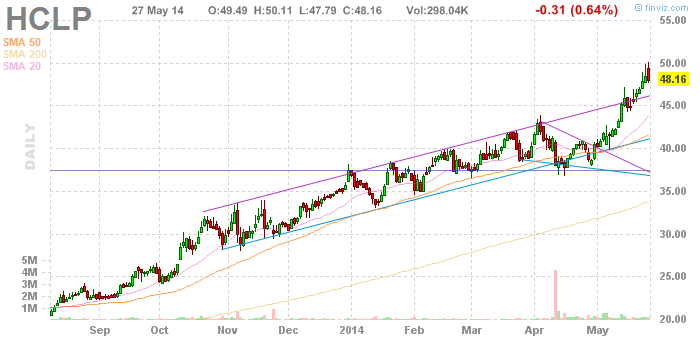
HCLP this one has been on fire average price 38.88 (not including the dividends)  Probably a bit overheated and a pull back might be needed. I would love to just let this one ride for the year and take a long term capital gain. 

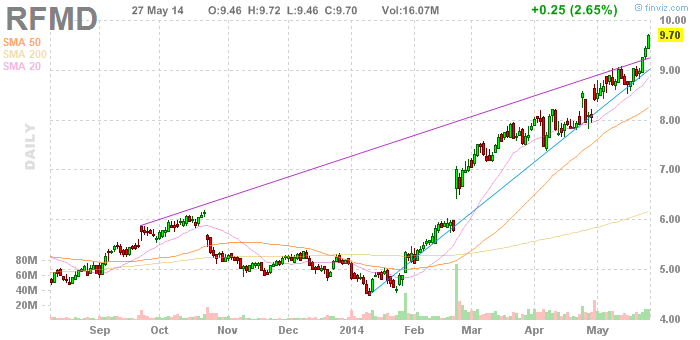
RFMD: Another melt up type stock.  In at 7.48.  Unfortunately,  I reduced my position size by 20% on that big red bar (for a small profit) in April.  Since May this has been off to the races.


NOK Average $4.43 This was my star of last year.  After a lot of consolidation between 8 and 7 NOK looks poised for another run if it can get past 8.  It's picked up some price targets and announced a share buyback  and a .51 dividend.  (we'll call that a reward for my patience after they cut the dividend shortly after I bought)  Obviously, this has paid off well for me and I want to see what it can do now that it is free of the handset division.

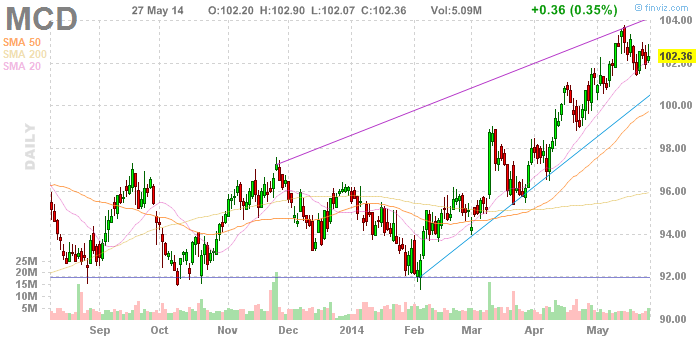
MCD: Avg. $100.28  continues to put in a nice little trend.  Slow and steady.  The 20 MA has acted as support.  If the market stays strong I would expect the next leg up to 104-05. I have no big expectations here, but it's a nice place to park some cash 3%+ dividend.

GFA: the dog of the group avg. 3.42 The breakout failed (or is failing?)   I was hopeful that the Brazil Rally would move this up and it had looked ready to breakout.  And then it went the opposite direction.  I cut my position size by 1/2 today and will dump the rest on close below 3.  Just under a 1R loss right now.   EWZ and many of the leading Brazillian stocks recently sold off.  Hopefully they can catch a bounce.  If not there's R. I. and C. of the Brics


SHORTS:
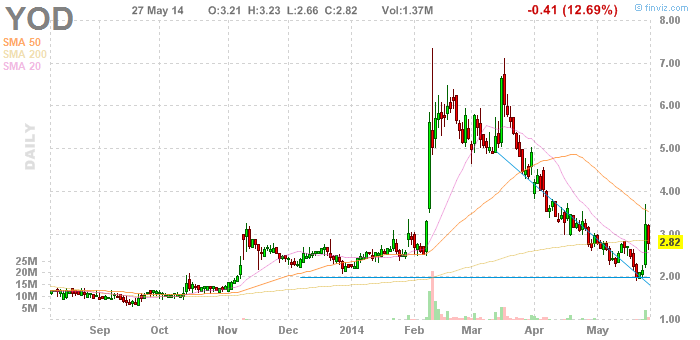
YOD This is what I love to see on a day after I take a short position.  -12.69% the next day. If only every trade worked on this well.   I anticipate as volume dries up this will drift lower.  There are likely people that bought the billionaire news at 3.20 or higher who are now trapped and when they capitulate YOD should see new lows.


Monday, May 26, 2014

YOD: Still nothing to see here.

On Thursday, it was reported that Xeuchu He, a Chinese billionaire Picked up 2.2 million shares or so.  It was also reported that Shane Mcmahon picked up 24,600 shares.  I had no position when this happened but the market certainly liked the news and YOD closed up over 50% on huge volume.  

The question I must ask is whether, does these events change my analysis and conclusion that YOD is fundamentally flawed.  I conclude that they do not and have re-entered my first tranche of my short.

  • The Shane McMahon Buy
As I discussed in the context of my review of YOD's earnings this stock is being heavily diluted and sold by insiders.  1.3 Million shares were added so far this year.  

Now Shane McMahon files an form F  announcing that Shane McMahon also bought 24,600.  shares on behalf of a trust Shane B. McMahon Trust u/a/ Vincent K. McMahon Irrev. Trust dtd. 12/23/2008, 24.  How is buy consistent with my conclusion that insiders are dumping?

 In filling out this form, McMahon had to list the number of securities owned following the transaction.  He lists 2,300,000


Now let's compare that to what McMahon declared in the February 6, 2014 Form S3:

C Media Limited (3) 9,142,8558,209,522933,333*
Shane McMahon(4) 5,782,9852,829,0982,953,88718.0%


The third column lists his shares following C-Media. 2.9 Million. In other words, he's cut his stake by 600K in just a few months. Heck, if you consider the shares he sold to C-Media (and I understand why he did as this company was out of cash and had received a delisting notice last August) He's cut his position by 40% in less than 6 months. 

 Second, I expect more selling from McMahon. I've noted that Shane McMahon has to exercise
 his warrants or he loses the right to do so and would make 4% interest. I base this conclusion on repeated statements in various filings, most recently the 10Q:


"Effective on January 31, 2014, the Company and Mr. McMahon entered into Amendment No. 4 to the Note pursuant to which the Note will be, at Mr. McMahon’s option, payable on demand or convertible on demand into shares of Series E Preferred Stock of the Company (the “Series E Preferred Stock”) at a conversion price of $1.75, until December 31, 2014. " 


The news that most people have been excited about is 2,285,715 share purchase by He. He purchased these shares from C-Media, which had recently purchased the shares from various insiders including McMahon.  The terms of the deal were not released.

So is this a game changer? Or is YOD still the same company losing 89 Million since it engineered a reverse merger with a public shell company, Alpha Nutra (PINKSHEETS: APNA) and became China Broadband in January 2007 (China Broadband changed its name to YOU on Demand in 2011.  (Don't you love "Chinese companies with American names) . YOD made  $138k in revenues last quarter.

I am assuming that He purchased the shares at a discount. I base this assumption on the fact that most PIPE deals are discounted (sometimes significant) and also on the short period that C-Media has held their shares.Some have suggested that C-Media sold their shares after buying from the insiders to lock in He's experience and connections.  I admit that initially thought this scenario was plausible but after more research I do not believe that this was the reason C-Media sold to He for several reasons.

First, Xeuchu He's fortune was made in mining. At Honbridge Holdings. Nothing in their organization chart would suggest a background, connections, or necessary experience in technology or video on demand, or even in China for that matter. He deals primarily with South American companies.

To that end, I began researching the link between Xeuchu He and Xeusong Song (the head of C-Media).  The two had been associated on numerous "blank check" companies also known as Special Purpose Acquisition Companies ("SPACS"). This is a process where He and Song, among other ("Jin Shi" a YOD board member) would create shell companies or engage in various reverse mergers.

SPACS were big in the 1980s but were abused by insiders looking to make a fast buck through the promotion of the stock. The SEC then began placing more restrictions including the amount of money that must be raised and price of offering, etc.. , Surprise the SPAC is back in China. In any event, Song seems to have the experience and connections for all of these deals and does not need to buy He's experience. For all we know the shares could be a thank you gift from Song to He for investing in the other SPACS.

Point being, I don't expect He to play a major role as an investor. He's not on the board, not part of management, doesn't have the authority to bind the company and does not have the background in the industry. And let's face 2.3 million shares of a $3 stock is not a whole lot of money to a billionaire to get actively involved.  By contrast he has his fortune tied up in Honbridge and his investors would probably not be pleased if he was avoiding his day job to work on a penny stock project.

Regardless of He's involvement, (even if he took the CEO) is that I don't think YOD can compete against multi-billion dollar companies on the same content. 

  • YOD still offers nothing that Chinese Internet Giants do not already provide.
YOD is going in to mobile now that its VOD cable has bombed. It is currently "pre-loaded" on one phone.  But guess what?  The mobile movie  market is already crowded with Billion Dollar Competitors:

Yoku yoku mobile app
LeTv http://mobile.letv.com
Tenecent's QQ http://film.qq.com

YOKU just missed earnings and got hit bad after guiding lower.  The reason more competition and increasing costs of content.  I thought the analyst's comments were very telling as they echo my sentiments on YOD:
“They are in a dilemma,” Echo He, an analyst at Maxim Group LLC who has a sell rating on Youku, said in a phone interview. “If they spend money on content, they cannot make profit. If they don’t spend, there won’t be viewers and ads. They are in a tough spot.”
Similar comments followed Tenecent's earning discussion on video.  So the big boys are all seeing compressed margins, the need to spend more on licensing and advertising to attract viewers. I don't see any possibility that YOD would be successful in such an arms race when it does not have the content, the infrastructure, or the money to advertise.  And the 138k in revenue demonstrate that it has not been successful.

In conclusion, the YOD is still the same company with contracting revenue growth.   It's my opinion that day traders took the news and ran with it. Momentum always dries up without earnings. And as YOKU demonstrates revenue growth will become increasingly difficult in this sector.

RISKING 1.5 R% on this one. 

Saturday, May 17, 2014

YOD: A company doomed to fail


 YOU ON DEMAND, ticker "YOD" has been pumped as the "Netflix of China."  But it's quarterly report demonstrate that YOD is not even the Netflix of China Town ... in Des Moines. 

I have repeatedly shorted this stock and did so again after earnings. I will continue to add to my position as the Quarterly Earnings report demonstrates that this company is doomed to fail.

Here is how I read the quarterly report of YOD and other pumped companies:
  • DETERMINE IF STOCK IS BEING DILUTED
    If a company is in a start up stage, you want to ensure that the insiders are committed to the long haul and not in it for a quick buck--the hall mark of a pump and dump.  So when I see a questionable company, I like to determine if and how much a stock is being diluted.  This will often take the form of convertible warrants and can be determined as follows:
Annual and quarterly reports will always list the number of shares outstanding as of the last date before issuance of an earnings report. The earnings data may in excess of a month a way.  This information lets you look into the future a bit.  

YOD is being diluted:
First page of quarterly report:

"Indicate the number of shares outstanding of each of the issuer's classes of common stock, as of the latest practicable date: 16,553,022 shares as of May 15, 2014."

Now let's compare that number since quarter end.  March 31, 2014.  We can do so by looking at the the Shares outstanding on the quarter.  An earnings report will compare quarters so we see that from March of last year that over 1.3  Million shares were added over the year:


       Basic15,931,39414,602,196
       Diluted15,931,39414,602,196

From the annual report, comparing 13 to 12:

Weighted average shares outstanding

       Basic

15,226,21611,099,746
       Diluted

15,226,21611,099,746


SINCE DECEMBER 31, 2013 the Shares outstanding have increased by 1,306,806.  This Stock is being diluted faster than a Dewars with two ice cubes. 
  • Assess Cash position and burn rate:  Obviously, you want to make sure the company has enough funds on hand to pay its bills and pursue its business strategy:
ASSETS
Current assets:
 Cash and cash equivalents$17,954,910$ 3,822,889


Wow, a huge increase in cash! YOD company must be raking in the profits right?  Not exactly.

Digging deeper we learn than it raised 25 Million dollars over the last year by issuing warrants.  They also sold off their broadband subsidiary. Of that, it now has about 18 Mill left.  Next, we determine whether the company is cash flow positive through ordinary operations:


Revenue$ 137,681$ 938
Cost of revenue875,938848,585
Gross loss(738,257)(847,647)
Operating expense:
       Selling, general and administrative expenses1,640,6401,983,736
       Professional fees185,484251,434
       Depreciation and amortization149,960292,833
Total operating expense1,976,0842,528,003
Loss from operations(2,714,341)(3,375,650)

*The 2013 earnings are a pro forma to account for a discontinued broadband business. (I'm somewhat skeptical of pro formas as companies can manipulate shares of the discontinued operations to show growth in the current business)   According to the YOD's annual report it list the discontinued operation as being profitable.  A question I have not answered yet is why they would get rid of their business that was at least marginally working?  But since that business is gone, I'll focus on the left over carcass. 

Currently, They currently lose money on every sale. They spend $8.75 for every $1.37 received    On top of that they have the other operating expenses which accounts for an additional loss of 1.9 M on the quarter.   At the current rate they'll lose 10.7 Million for the year. Leaving them with just $7.2 for next year.  YOD does not have sufficient cash to get through the next year.  
  • Is the Company's Business Plan working?
All companies hope that at some point they can generate sufficient revenues to cover the cost of revenue and the cost of operations and at some point even make a profit.  Given the struggles YOD has had I see little value in discussing profitability as it is not really relevant that the company has lost nearly $89 million since it began.  It's all about revenue growth.  It is imperative that the companies grow and given that there is less than 2 years of cash remaining, it is imperative that YOD grows very quickly.  Unfortunately, for YOD that is not what is happening.  Q4 2013, revenues were 163,000  and first quarter earnings were down to $137,681. YOD is clearly not growing as it had planned.
  • Will a new mobile business Strategy the Savior?
YOD apparently is of the belief that mobile will be the future.  It currently is on 1 cell phone, the Huawaei Mate and can provide up to 2 movies a week to subscribers. I seriously doubt that this strategy will work--are people really going to rent movies to watch on a 4 to 6"  screen?  I'm very skeptical. And  the revenue decrease demonstrates that this strategy is not working yet.  

Setting aside my skepticism and lack of tangible revenues, let's assume for the sake of argument that such a business plan is viable.  However, to implement this strategy it is imperative to advertise this new service, develop back end support, obtain the available servers and equipment necessary to run such a business.  In other words, to obtain mobile revenues YOD  requires a substantial additional investment.  Pursuit of mobile revenues will necessarily increase the company's losses.   And it does not have any margin for error, with the less than 2 years of cash it has remaining, which will mean to  company will need to raise cash causing more dilution.

In its own words:
 "we have access to additional funding through various methods including utilization of our $50 million shelf registration of which $47.3 million is remaining as well as other means of financing such as debt or private investment."
Just so no one is surprised when the next wave of dilution comes. And then the "going concern" notice. "These conditions raise substantial doubt about the Company’s ability to continue as a going concern."
The other "Analyst" --Chardan Capital-- has a $10 price target and recently opined that this could be a take over target.  I have not identified anything that YOD has that any potential suitor would not be able to acquire on their own for far less than $40 million.  

But Chardan and its executives own over 2 Million warrants.  (incidentally Chardan's founder is the brother of YOD's CFO March Urbach)  And the 10 price target is supposed to be objective, yea right. In addition,  In the quarterly report,  YOD discloses, "The Company is committed to paying service fees to certain consultants of $25,000 through the second quarter of 2014." 

Companies that pay for play, nearly always crash after the promoters have cashed out.  Given what we know about the ongoing dilution--nearly 9% year to date.  YOD is actively being sold and will be continue to be under tremendous selling pressure. 
  • The Competition is intense and the competitors are Goliath's
As I have pointed out on stocktwits, this notion that YOD has exclusivity or is a leader is a complete myth. Finally, YOD has acknowledged as much at the Conference Call:
The market for video entertainment is subject to continuous change and aggressive competition. Our primary competitors include companies that operate online video voice type in China, such as iQiyi, Youku, Tencent and Sohu. They all carry a very large amount of the video content, including Hollywood and domestic movies and they compete on the variety and freshness of the content, in order to drive Internet traffic to their websites. 
YOD is competing against companies that are worth many billions of dollars with the same content.  Who has the infrastructure and ability to spend money on advertising?  YOD will lose that battle. 
Conclusions

  •  The Q1 report suggests that YOD is doomed
  •  Revenues are decreasing, 
  • YOD losses money on each sale
  • YOD does not have sufficient cash to get through the next year. 
  • More dilution is likely
  • Insiders will continue to exercise warrants keeping YOD under pressure
  • It will need substantial additional funds to pursue its mobile strategy.  
  • Competition is intense and YOD offers nothing to consumers that Chinese Internet giants do not already have.
Nonetheless, some people spent 15 minutes reading an article on seeking alpha, by an anonymous author who created his profile the day he published his first article which calling YOD the Netflix of China. Based on that pump, they continue to think will become a double and triple digit company. I plan to go point by point through that nonsense, but my conclusion is don't buy the hype. 

Thursday, May 8, 2014

YOD: Shorting the aftermath of a Pump and Dump for profit.

April 6 , 2014
$YOD trade diary.  I got short at 5.08 in A.H. after earnings.  They missed but it was bit up for a few minutes anyway.   It last closed at 4.09.  I believe there is more down side.

On Friday there was news of a partnership with Miramax for mobile.  YOD traded as high as 4.99 premarket but sold off quickly opening at 4.50.  It was met by heavy selling that pushed it as low as 3.80.    It then preceded to churn most of the day.  I don't believe that support at the 4 will be able to hold.  Each time it dropped below it came from a great distance which I believe reflects exhausted seller.  Note that the volume was not heavy below 4.   I believe that it was a few stop orders that triggered .10-.20 drops after that level rather than being seen as a target for short selling.  Should there be a push below 4,  $3.80 is unlikely to hold and this could fall very fast. 

 I'm targeting $3.30, which is where it launched before the pump. The MACD showed very bearish divergence on the second push to $7.00.  This should have been the sign that this was finished  to the upside.  But the bearish MACD keeps getting stronger as the stock falls. 


April 7
More selling, 4 broke but it felt more like a slow grind rather than the sharp sell off type move


I covered at 3.68, earlier than my profit target of 3.30 for several reasons.  First, the sell off was not very sharp today and was indicative of ambivalence more than panic.   Although I think it continues to go lower, there are better plays than waiting to squeeze every dollar out of this trade. Second, the overall market has been down pretty sharp.  There was some bounce movement in the momo players towards the end of the day, which could trigger a sharp uptick across the board.

Overall 5.08 - 3.68 in a week.  For a $1.40 gain or 38%. That's a home run. 

April 16, 2014

I reconsidered my belief about the grind, and re-shorted. After trading to the 3.30 range.  YOD popped back up again to 3.70.  I again shorted it finally covering at 2.38

Will it go lower?  Probably, but in the 2.30s I did not feel that it continues to make sense to hold the short position. It will probably be a slow grind to its death. But there are probably better uses of the funds than waiting for a 2.00 move, which may take 2 years.