Showing posts with label PME. Show all posts

Tuesday, January 24, 2017

1/23 -1/24 Trades- Sector risk back on

1/23  -- Did a great job of being disciplined, Closed OCLR for even.
Market breadth flags here.

Trade Spreadsheet.

1/24
WATT  - nailed on downgrade
Made 1.05 on this trade, probably covered too quickly but I question whether this was my trade to begin with.


Wednesday, February 11, 2015

Closed PME, EMES (PUTS) NFLX, WATT

I had to do some pruning.

First and worst, PME.  This turned out to be a pop and drop.
Again, I remind myself that first day "EPs" usually aren't and is best to let them settle in.

Entry 4.16
Exit. 3.30


EMES:
This one worked much better. Still I closed because the range is contracting and I'm on front month OTM puts.

Entry:  1.80
Exit 1: 2.60 (44%)
Exit 2. 2.35 (30.5%)


NFLX:
NFLX looked so good early.  I moved my stop up and then NFLX faded taking me out.  I took gains out of the trade but it feel like a participation medal given the 20 pt move I could have caught.

Entry: 451.37
Exit 1: 455.1
Exit 2: 454.31
Exit 3: 455.07

WATT:
My test position broke to the down side. So I banged it out.
Entry:10.28
Exit 9.67


Tuesday, February 10, 2015

Trade Journal, Position summary Many moves, many profits.

Today was one of those days where most things work.


My BOXand ARRY buys gap, Sold off half BOX, the remainder runs.  manage risk sell off some ARRY I can live with that. RESN runs I sell into that run.  AAPL proves why it the worlds most valuable company.  My calls are up big.  My EMES puts gain as EMES falters.  I bought some NFLX it runs,  Bought some GNVC and HPJ off bounces  If they firm up I'll be sitting very pretty and then  TWTR looks like NFLX q1 2014 as it rallies off the gap test and finally I add PME in A.H. off news that it has eliminated its V.I.E. structure and received an investment which would value the company at 800 million or a stock price of 9.50

 I haven't taken stock and given the full run down my holdings without further adieu charts:

BOX:
IF only every stock I bought did this in yesterday at 19.30 close today 20.99.  Still I think this has a chance to take back its IPO high close of over 23, we will see.

ARRY:
Wedge breakout.  I did a partial sale at 7.98 because it gapped in the morning and faded.  It then regained some strength.  This will be off to the races if it can get some space over 8.
EMES
Continuation to the downside following the rejection by the 10week avg.  If another continuation day look for low 50s
HPJ 
I liked the bounce and reversal off the gap.  My working theory is that this will now come around to make another run at 6.00
Entry 5.40


NFLX has that power move potential.  I bought today at 451.37 and caught a decent piece of this 10.00 move. I sold off half the position at 455.10 to manage risk.  If this can get some continuation.  I  would think $475 is in play over the next couple of weeks.


AAPL gets the break above 120 and my 115calls are now deep in the money.
No changes to position, none anticipated as this run is just starting looking for 128.

TWTR:
A power move gap, which has thus far stuck.  I bought this move as TWTR rallied off the gap.  The low of the day presents a great stop making this a well defined trade.  If it gets over 48 I will consider adding as it will break range and show trend.
PSXP
Nice consolidation, which is needed to push over 80.  I've cut down my position.  I will re-initiate my position on a a pull back to 75 or a break above 80.

GNVC: 
This is a high momentum stock that they attempted to breakdown.  Right on the trend line it rallied hard.  That tells me this is still "in play" I'll take a piece here at 4.00.
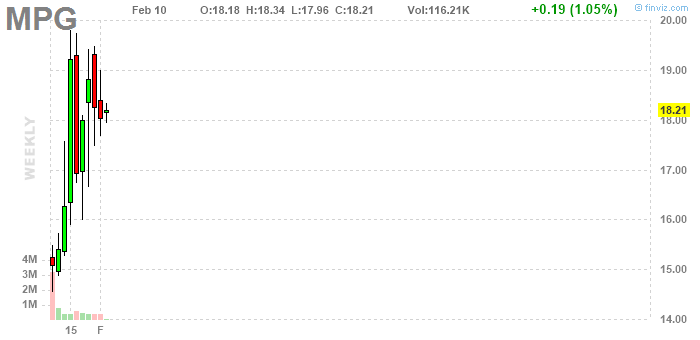
MPG:
Weekly.  Still holding a small position.  This has had some momentum and could be a decent winner if it gets going.  Right now this range is getting very tight

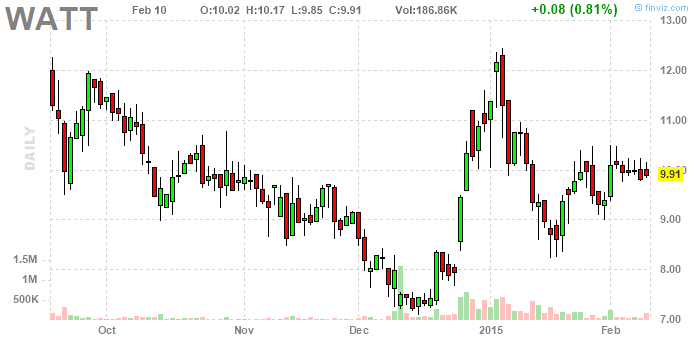
WATT:
This company has a really cool product which lets you charge wireless devices without plugging them in.  It won a number of CES awards.

 In many ways its similar to RESN.  I've bought  the consolidation here small, which I'll cut if it breaks to the down side and add if it breaks to the upside.


The Grand Finale 

PME

I'm treating PME as An episodic Pivot  Here's the news:

 PME is "a global fishing company based in the People's Republic of China (PRC), today announced that the Company's wholly-owned subsidiary, Fujian Provincial Pingtan County Ocean Fishing Group Co., Ltd ("Pingtan Fishing") has entered into an Investment Agreement ("Agreement") with China Agriculture Industry Development Fund Co., Ltd, ("China Agriculture") pursuant to which China Agriculture will invest RMB400 million (approximately US$64.0 million at current exchange rates) into Pingtan Fishing for an 8% equity interest in Pingtan Fishing's operating company. The investment values Pingtan Fishing at approximately 5 billion RMB, or US $800 million at current exchange rates. The closing and funding of this strategic investment is expected to occur no later than February 13, 2015."
END of VIE structure!
When I previously looked at this stock I found the VIE structure too complicated and too sketchy to invest.  Today's news removed my objection:
"Pingtang terminated its existing variable interest entity agreements, or VIEs, as permitted by the laws of the People's Republic of China. This provides the shareholders of Pingtan Marine Enterprises with direct ownership of its subsidiaries rather than contractual ownership through the VIE structure. "
  • PE Ratio of 2!
This stock initially came up in a scan due to its ultra low PE ratio.  I passed however, due to the VIE structure.  Now that that appears to be resolved this stock is ultra cheap and now offers direct ownership. 
Summary 
I believe that this is a game changer and bought at 4.10 and 4.20  in A.H.  Even with the appropriate China discounts PME should trade north of $7. But again, It is Chinese and I'm not going to go overboard until I get my hands on the SEC filing for this deal.

Tuesday, June 3, 2014

PME: Cutting bait.

My initial research revealed that PME was  possible deep value play, trading below asset value. Subsequent research revealed that there was still too much risk in this trade and I've elected to close it before I get trapped.

My concerns include  the fact that the Roy Yu, the CFO, previously was the CFO of Lihua International, Inc. (NASDAQ: LIWA) The SEC recently suspended trading LIWA because of non-compliance with financial reporting obligations.  I don't want a CFO of a company that I would own to have previously headed a delisted company due to improper financial reporting.

In addition, PME is guaranteeing numerous loans in the name of the wife of the CEO, but admits the pleadge has no beneficial purpose to the company.

" We have entered into certain pledge agreements pledging 22 fishing vessels as collateral to secure a loan to Hong Long, a fishing company controlled by spouse of Mr. Xinrong Zhuo. The pledge has no beneficial purpose for us and we could lose our fishing vessels if Hong Long were to default on the loans, which could be detrimental for our operations."
Trade Summary:
When your reason for taking a trade is in doubt, get out. I took about $100 loss on  PME rather than stay in and hope for a profit. This is too thin and the Risk level I planned for this  trade did not account for a delisting. Given the history of executive delisting could be a legitimate risk. Given the risk that the company is taking without a benefit, I would not be surprised if the insiders leave an empty shell for the American Investors. I'll fish elsewhere.

Saturday, May 31, 2014

PME: Fishing for Value.

Benjamin Graham referred to his style of investment as "Cigar Butt" investing. He would look for companies that had been largely been discarded but still had a few puffs left.  Graham reasoned that such companies would trade at a discounts to asserts and would thus provide an opportunity to realize a substantial profit with minimum down side risk.  

During the course of researching YOD and its new billionaire investor, I believe that I may have found a company fitting Graham's criteria.  One of the companies, Xuechue He, (who purportedly is the 38th richest man in China was involved was Pingtan Marine, a company largely ignored (look at that volume 46,980!):

ORIGINS

PME was has its origins in a "blank check" or "SPAC" company called "China Growth Equity Investment Ltd." (CGEI).  CGEI acquired a number of fishing industry companies: Merchant Supreme, China Dredging, Fujian Xinggang Port Service Co., Ltd, Fujian Provincial Pingtan County Ocean Fishing Group Co., Ltd, and rolled them out as new company called Pingtan Marine Enterprises.  After this roll up,  PME has companies that  which  presently looking like this:


PME's Operations


"We are a marine enterprises group primarily engaging in ocean fishing through our wholly-owned PRC operating subsidiary or VIE, Fujian Provincial Pingtan County Ocean Fishing Group Co., Ltd., or Pingtan Fishing. We harvest a variety of fish species with our owned and licensed vessels operating within the Indian Exclusive Economic Zone and the Arafura Sea of Indonesia. We provide high quality seafood to a diverse group of customers including distributors, restaurant owners and exporters in the PRC."
(From annual report)

In other words, there is nothing ground breaking or high tech.  They currently own 126 ships boats and fish off of India and the Arafura Sea.  The boats are valued about $1Million a piece.  They were independently appraised, and the appraisals for each ship are available on the company's website.  PME recently announced that it had ordered 25 new boats, which will replace some of the older ships in the fleet when constructed.


Why I'm Intersted

The Chinese fishing industry is growing, but I don't particularly care.  What interests me is that PME is trading below its tangible book value-of $3.45. In itself, that would not get me excited as numerous companies in declining industries trade below assets. For example, coal companies such as Arch Coal trade significantly below book. (ACI trades at 3.50 and has a book value of 10)  PME, however, also has a p/e ratio of 2.7.   In other words, we have earnings that are growing and it trades below book.  This is one that just might fit Graham's criteria.  Indeed, PME trades well below its "Graham Number" of $8.89


The first quarter highlights:
  • Revenue from continuing operations ("fishing business") increased 233.4% to $65.6 million from $19.7 million, primarily due to increases in sales volume and unit selling price.
  • Gross profit increased 347.1% to $24.0 million from $5.4 million, and gross margin was 36.7% compared to 27.3%, due to an increase in unit selling price, change in product mix and tighter control on cost of revenue.
  • Net income from the fishing business increased 393.1% to $21.7 million, or $0.27 per diluted share, from $4.4 million, or $0.06 per diluted share. 
So we have growth last year. PME has provided revenue guidance of for 2014 of $80 and $85 million.  Compared to other fishing industry companies PME is incredibly cheap: 


It's always a fun game to play the "if it trades at the average what would the price be " game.  Based on EPS guidance.  PME would be $17 if it were to approach industry means.

RISKS
So we have a $17 stock trading below book value at $3.20, slam dunk right?   Not so fast. As with any Chinese stock there first question is whether you can trust the numbers.  The Company hired a public accounting firm that is supposed to verify compliance with GAAP standards, etc..  So if the auditor does its job, this still sits pretty. That being said, I  would be still very skeptical if I saw widespread warrant exercising and dilution.  Fortunately, I do not see dilution. The number of shares outstanding has remained at 79,055,053 since 2012. 

Two other things raise at least some yellow flags.  The the company's "in the press" section contains Seeking Alpha articles and by "the street" recommending its stock.  I'm not big on companies that promote their own stock rather than their companies.  But this is not necessarily a big deal, the company sells fish at market prices so there's no need to brand or advertise, etc..  Still just keep the self promotion on the watch list.

In addition,  there are numerous closely related party transactions.  Some of these are because of the roll up where individuals involved in the subsidiaries.  This should cause some questions to be asked but it is not a reason to totally stay away. 

Ironically, one the things that has eased my concerns is that PME is taking on new debt to finance the new ships.  Small cap companies with debt will outperform those with no debt.  To some degree, the additional debt provides some assurances over the finances of PME as what lender would provide such loans without confidence of being paid back.


CONCLUSION

This is a fishing company. The industry is not complicated and should not be that subject to trends.   We know the company hard assets from the boats they owned and were independently appraised.  Because PME trades below book and earnings have increased, I feel that it is worth the risk of taking a position and I've done so.

Trade RISKS PME is thinly traded, so position size should be 1/2 to 1/3 of normal position size.  Also, given the liquidity issues, do not use a hard stop.  My mental stop would be 3.00 for less than 1R risk.