Showing posts with label Shorting. Show all posts

Saturday, November 8, 2014

Closed YOD short

I closed my YOD short at 2.86.-- from my 2.97.  Another winner on YOD (I'm now 6 for 6 on my YOD short sales).  This is not one to boast about as I was unable to get any size on the trade. I attempted to borrow shares throughout Thursday and Friday but to no avail. To that end, this trade stopped being worth my time as there are better opportunities.  

That being said, If a block of shares were to free up, that gap fill still looks tasty. 


Saturday, November 1, 2014

Opened YOD short

YOD got a fantastic pop on rumors that BABA was interested in purchasing it via "unconfirmed market chatter." As with most stocks that pop due to buyout rumors  I have little doubt that YOD will fade completely.

I've have a very good handle on YOD.  I have traded this stock a number of times during the past year and recognize the absurdity of such a rumor.  In addition to YOD's wide spread insider dilution via warrant exercise the economics of a YOD / Baba deal simply do not make sense. BABA already owns 16% of yoku and just launched as a new platform to market YOKU's videos.  So what would buy an American company with non-exclusive licenses to compete with its partner?  That won't happen.  Despite what the pumpers on twitter were saying.

Eventually the momo traders came to their senses and started to fade this stock. Enter my short opportunity:

Entry 1: 2.39
Entry 2:  209
Avg. 2.19
Risk: 1.5R


A very long wick on that daily candle which suggests that this will not be a multi-day pop. This was  a 1 and done type move, imo.  Given the speed and volume on the  sell off I increased my position by 2/3 going into the close. 


Under normal circumstances,  I would target 1.85-1.95 range and I'll probably partially cover in that range.  I suspect, however, that due to the volume there will be some new bag holders that are now trapped.  I very much doubt anyone bought this as a long term hold as the fundamentals are unproven and have underperformed for years.

2 years ago Analyst forecasted revs of over 20 mill-- not even close, Last year $15  mill. nope.  Early this year $9 mill.  The company now says $3 mill.  As pathetic is that is for a company that claims as an 11 million viewer market, the company has earned less than 200k in both Q1 and Q2.   I'll  target 1.65- 1.55 within a few days as rally attempts fail When the reason for the buying spree has evaporated, stocks tend to over-adjust the other way so this has the potential to go even lower near term.

Monday, October 20, 2014

Closed OBCI

OBCI sold off again. Rather than attempting to hold out for the last dollar I decided to close it out as the volume dried up.  There are now better opportunities out there. 

Trade summary:
Entry:  4.46
Exit: $4.14 (+7.17%)
.26R -- I wasn't able to get filled with the size I had hoped so this round turned out to be a rather uneventful 7% move.  


Friday, October 17, 2014

Opened OBCI- short round 2.

A few people have come to believe that OBCI is an ebola play because it now owns a disinfectant called performacide -- which it purchased 2 weeks ago for a mere $150,000.

I previously shorted this stock successfully from 5.30 to 3.95.  I was very pleased to see it bounces again on low volume, which allowed me to take another shot at it.  I was able to get a tranche filled of my short @ 4.47.  I had orders to short more, which did not get filled as this stock couldn't get a bit higher. 


A weekly chart really demonstrates how extraordinary this recent "ebola" move has been in relation to obci's trading history.


This has set up nice for a pop and drop rather than an "EP":
  • Sustainability of New Demand, revenue and earnings?   
Stocks like LAKE and APT have products that fill a demand that is currently unfilled.  There will be a shortage of hazmat suits, etc..   .  Yet every hospital, restaurant, airport, and most homes already have products that are more than capable of killing Ebola.  All you need is a commercial grade disinfectant  there are hundreds of products that fill that need.  But don't take my word for it, per the CDC
"Ebola is killed with hospital-grade disinfectants (such as household bleach)"
Heck, just in my basement, I already own at least 3 cleaners which I've owned for years that could kill Ebola: 

  • OdoBan® is an EPA registered disinfectant. The EPA Registration No. is 66243-2.
  • OdoBan® meets AOAC efficacy standards for hospital disinfectants.
  • OdoBan® meets AOAC efficacy standards for non-food contact surface sanitizers on hard non-porous surfaces.
  • OdoBan® is a Hospital Disinfectant Cleaner that is effective against a wide variety of Gram positive and Gram negative bacteria. It is also an excellent deodorant and leaves a clean fresh odor. Respiratory illnesses attributable to Pandemic 2009 H1N1 are caused by influenza A virus. OdoBan® is a broad-spectrum hard surface disinfectant that has been shown to be effective against Influenza A/Hong Kong and is expected to inactivate all influenza A viruses including Pandemic 2009 H1N1 (formerly called swine flu). OdoBan® has demonstrated effectiveness against Influenza A/Hong Kong and is expected to inactivate all influenza A viruses including Pandemic 2009 H1N1 (formerly called swine flu)
Simple Green D (my wife likes organic shit) but again it would serve the same purpose
  • Hospital–grade disinfectant
  • One–step cleaner and deodorizer
  • Fresh herbal–pine scent
  • High dilution ratios for great economy
Ideal for airplanes, airports, athletic facilities, cafeterias, clinics, day care centers, emergency vehicles, exercise facilities, food service facilities, hospitals, hotels and motels, kitchens, locker rooms, nursing homes, prisons and correctional facilities, public restrooms, schools and colleges, anywhere cleanliness and disinfection are necessary.
Clorox Bleach.  Perhaps  most significant regular, ordinary bleach will kill ebola.  No body needs to turn to some cleaner they've never heard off out of fear, They can go to the products they already buy such as Clorox Bleach, which is more than capable of killing ebola.  


"This week our company took a first step, donating 12,000 64-ounce bottles of Clorox® bleach destined for West Africa. " 

Incidentally, Clorox's initial donation has a market value of nearly the entirety of OBCI's purchase of performacide. 

Consequently, I would question whether there will be any uptick in profits at all.  Any revenue OBCI receives would be mere fraction of the purchase price it paid for Performacide.  Obviously, if performacide were generating 150K in profits a year, it would have sold for a multiple of its earnings (P/e ratio).
  • But isn't Performacide the best, Ebola killer out there?
Anyone that makes such a claim has obviously not read the specs for Performacide.  
"Solution will be usable in 60 minutes (1 hour).
NOTE: Allow ONE (1) HOUR BEFORE USE TO ENSURE SOLUTION REACHES FULL STRENGTH. Be sure to agitate upon addition of the pouch to the water and before initial use. Temperature must be kept between 20-25oC. "
So we have an Ebola outbreak and I have to choose how to clean it up.  Do I go with the product such as bleach that can be used immediately or do I pick Performacide which I have to wait an hour to use?

  • Soft goods, such as linens, clothes, etc..? nope:  Performacide is a "DISINFECTANT OR VIRUCIDE* FOR HARD, NON-POROUS SURFACES? 
  • Buyout potential
I've seen bulls now make the claim that this is a "buy out candidate"  because it has tight insider ownership.  I can't tell you how many times, I've heard such claims by bulls (usually with losing positions that are holding out hope of getting even) that xyz is a buyout candidate.  Anyway, here is why that will not happen.  

Entities that buy companies are typically not stupid. They are not going to pay an "Ebola" premium for a company such as OBCI that has not demonstrated any revenue acceleration, but has shown stagnate revenue growth over the past few years:


Another reason I do not see a buyout is that the company insiders rely heavily inn the company for income.  In addition to their salaries there are a number of "Related Party Transactions" that   app are to make more for the insiders than their OBCI day jobs: 

  • During the three and six months ended June 30, 2014 and 2013, the Company sold products to companies affiliated with its Chairman, President and Chief Executive OfficerThe affiliated companies distribute the products outside of the United States and Canada. 
    • Sales to the affiliated companies aggregated approximately $295,000 and $469,000 during the three months ended June 30, 2014 and 2013, respectively, and approximately $1,008,000 and $940,000 for the six months ended June 30, 2014 and 2013, respectively. 
    • This begs the question why is the CEO's personal companies distributing OBCI's products instead of OBCI?   
  • "the terms of sale to the affiliated companies differed from the terms applicable to other customers ..."  OBCI then goes on to attempt to justify the sweet heart deal the CEO's affiliate company is getting  "the affiliated companies bear their own warehousing, distribution, advertising, selling and marketing costs, as well as their own freight charges" 
And there's more:
  • "A subsidiary of the Company currently uses the services of an entity that is owned by its Chairman, President and Chief Executive Officer to conduct product research and development, marketing and advertising. .. the Company paid the entity approximately $10,500 for each of the three month periods ended June 30, 2014 and 2013, and $21,000 for each of the six month periods ended June 30, 2014 and 2013."
  • The Company leases office and warehouse facilities in Fort Lauderdale, Florida from an entity controlled by its Chairman, President and Chief Executive Officer.  
  •  A director of the Company is Regional Executive Vice President of an entity from which the Company sources most of its insurance needs at an arm’s length competitive basis.  During the three months ended June 30, 2014 and 2013, the Company paid an aggregate of approximately $98,000 and $150,000, respectively, and during the six months ended June 30, 2014 and 2013, the Company paid an aggregate of approximately $315,000 and $333,000, respectively, in insurance premiums on policies obtained through the entity. 
These types of transaction should always raise red flags. Frankly, If I were a shareholder I would question the property of such transactions. If these deals are worth doing, why isn't management doing them for the company instead of for themselves.  Got fiduciary duty? Well at least we know  that management would be insured against such a claim from the policies they purchased from their director's company. 

I've worked with numerous private equity groups.  There is no way that investors are going to buyout a company that has all these additional contracts to benefit management's own companies.  I would also suspect that management has no interest in selling given the deals their own companies are making off the backs of the OBCI shareholders. 

Q2 results that saw EPS growth of 137% doesn't that demonstrate huge growth?    not so much turns out.  ---  Consider Q1 Revs.  Down pretty big.  


So what happened?  Well it turns out that Q1 was pretty cold in most parts of the country and customers delayed their purchases that they would have made in Q1 to Q2-- so Q1 looked horrible and Q2 looked amazing.  Combine q1 and q2  them Q13 had 14.49 mill versus 14.72 mill in revs for Q1.  Not exactly setting the world on fire with that type of growth.  

Summary
  • Stock price has increased purely on Ebola hype
  • OBCI is unlikely to ever realize any revenues due to that hype
  • A buyout is a pipe dream of desperate longs. 
  • Current earnings and rev growth do not support the stock price pop
  • Price target-- Back to business as usual. $2.95-3.25

Tuesday, October 7, 2014

Opened Lake Short. Position Trade. Short Hypothesis.

The "ebola stocks" have been running as of late  and I've participated with TKMR.  As much as I've enjoyed this type of run, it gets to a point where things start to get out of hand.  LAKE.  Lake makes a variety of protective clothing including Hazmat Suits, which can be used to protect health officials against Ebola.  So naturally it puts out a press release that says it has suits for Ebola and it becomes part of the Ebola stock sector and it's stock rockets forward. 

Today,,TKMR pulled back hard but  LAKE puts on over 13% today.  Although I'm normally hesitant to short moves like, this this is the 3rd pop and is  a sign of tiredness. I shorted at 10.30. I started small as I'll accumulate over the next few days to weeks.  I believe this retraces to 7. 


Here is what I see as the negatives:

  • There is Nothing Unique.  They make Hazmat suits.  So do dozens of other companies, such as  Dupont 
  • Weak financials
    • Company reported weakening U.S. sales last quarter:

"Q. What happened to sales in the U.S., it sounds like that was disappointing?
Christopher J. Ryan - President and CEOThey were a little disappointing on -- there were two -- three divisions that were up and two divisions that were down. The two divisions that were down were down more than the three divisions that were up." 

  • Focus of management   At the q2 CC. The CEO was discussing  about Yahoo message board posters 
  • "we have had a poster on the Yahoo message board, which has generated several inquiries from investors. Let me say this poster has long ago given up any pretense of being a concerned investor and is clearly a small group of former employees, who were former for good reason."
When a CEO of a company is reviewing the message boards on his company and then commenting about them during conference calls, it is typically not a good sign.  Perhaps, their efforts would be better spent trying to revive their sales instead of browsing their message boards.

  • Widespread false belief of government award
    •  Many people on stocktwits and twitter have stated that LAKE has a confirmed order for 160,000 suits.    Nope. 
    •  The state department is seeking bids for hazmat suits but there has been no award and certainly no award to LAKE.  Lake mention the bid in a press release and many assumed that they were awarded the contract. 
  • In the company's own words:
"the  materiality of this incremental demand is yet to be determined but rest assured that we have the appropriately qualified and specified suits and the manufacturing capacity to supply these garments."
 Great they have the suits, the question is and always was how many will be bought. 

  •  No record of successful sales to U.S. Government
    • Government contracts are  a matter of public record.  
      •  LAKE's government contracts to date have totaled: $21,370 in lifetime contracts.   Wow!  That's worth a 50% increase in a week. 
  • Biggest Shareholders sold out everything. 
  • Outrageous hype with leaders beginning to fail.  TKMR down from 30 to 22. 

  • Positives
  • Ebola has hype and the story could get hotter  before it flames out.
  • Tiny float. (a double edge sword of course)
  • Minimal Dilution to date
  • 5,358,509 shares as of July 2014
  • 5,360,681 shares


  • SUMMARY

    I've seen this scenario play out dozens of times. This will drop back to 5 or lower.  There are too many negatives.  The question is now only a matter of timing.  

    Monday, October 6, 2014

    Closed SA short

    There might not be much follow through on the long side.  The short side has fared much better either. SA looked like it was about to fall off the table on Friday. Today it popped back into consolidation.  I took a small loss .27.  I sized this one small given the level of selling in the gold sector so this did not hurt badly .28R  

    This is the type of Risk management I need to have on all my trades. 


    Day trade Short RBCN 18.8%

    The big news today was that GTAT declared bankruptcy and fell 90% from over $10 to under a buck.  I heard the news and immediately looked to RBCN. Down .04  I shorted it @4.46 and then the really fun began. This was a total avalanche.  I covered at 3.62, which turned out to be pretty darn close to the bottom. 

    Why did I cover @ $3.62?  When a stock encounters aggressive selling and then that action slows and some bids come in I find it best to close the trade. It worked. 

    Entry: 4.46
    Exit 3.64
    18.8%  (.85 R)


    Friday, October 3, 2014

    Opened Short SA

    SA broke out of consolidation to the downside. I entered a short position at $7.75 . This is essentially a mono burst setup to the short side.  What I like about it is that the 10MA held... The 10 has tracked the move both to the upside and the down side really well.  based on prior history a multi-week 15-20% move is possible if not likely.

    Entry: 7.75
    Stop: 8.07
    Target 6.75- 7.05

    Friday, September 19, 2014

    Closed SLCA Short.

    This is one I wish I had back.  I nailed the entry yesterday. 72.35 .  There was very clear topping action.   SLCA popped in the Morning off of news that Goldman Sachs upgraded EMES, it then faded.  I covered into the fade at 71.52 because I was concerned that the sector might rally as EMES did.  Nope. HCLP and SLCA faded.   A one day gain turn out to be decent, but I need to let the set up play out.  The lesson learned is trust the chart.


    Thursday, September 18, 2014

    Opened Short: SLCA


    I opened a short position in SLCA today at 72.34.  Why? after all it's close to a 52 high and has been fire.  Plus, I love the industry.  

    Not everything is well in the sand box.  There's heavy negative divergence on this last pop.  Nonetheless, SLCA is 13% above its 50MA, suggesting this expensive relative to its normal trading range. 

    Monday, July 28, 2014

    Closed: WMT, MTN

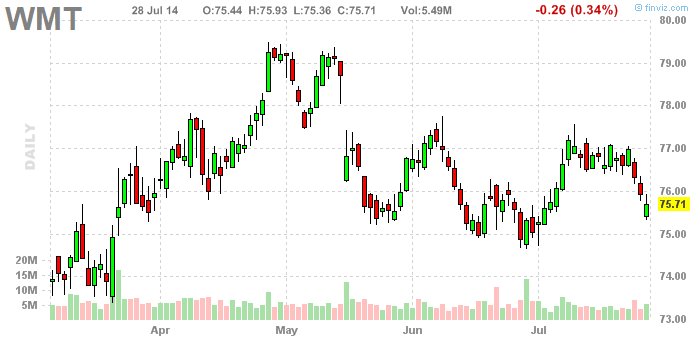
    WMT fell out of the consolidation which made a nice short opportunity.  In pre-market it fell as low as $75.07 before the bell.  I had attempted to get filled at .10 but it didn't happen.  It opened up @.44  I closed at $75.59.

    Entry 76.29  +.70  +4. R.     This was never going to be a big trade, I took what it gave... if only I was faster on the draw this morning.


    MTN
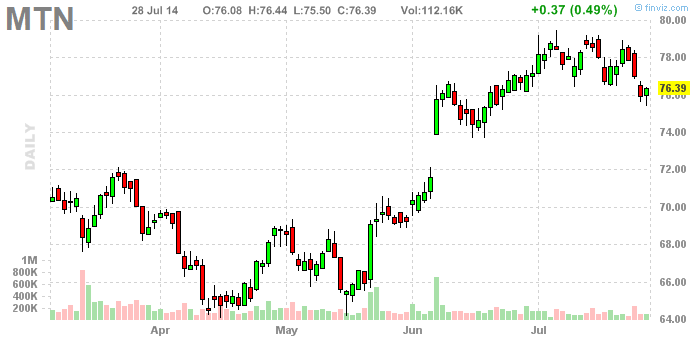
    This was a trade off the MACD divergence type top.  
    Entry: $77.35
    Exit.  Partial $75.55 (+1.80 ) and  $76.42.  (+.93)   .4R  This could have been a great exit but I only got a partial fill -- 25%  and then the bid jumped.  After seeing it was a reversal I decided just to end the trade.

    Nothing special.


    Thursday, July 24, 2014

    Opened: Short WMT

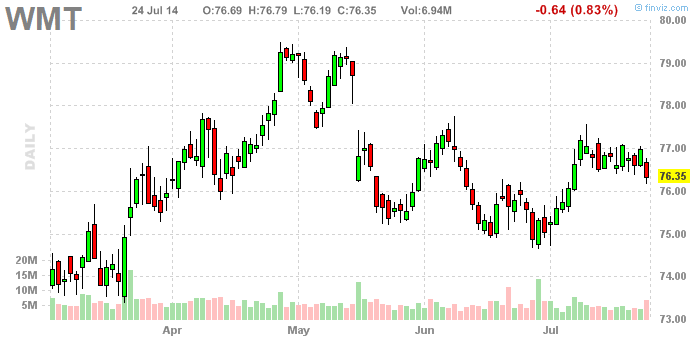
    Went short WMT witha tight stop at today's high.
    76.29, stop at 77.80  .3 R

    Possibly setting up for a H&S. Today slightly broke out of the range to the downside. Tomorrow will be decisive.   76 could provide some support but it it does not hold a decent 2 to 3 point move to the downside could start.


    Thursday, July 17, 2014

    New Short: MTN

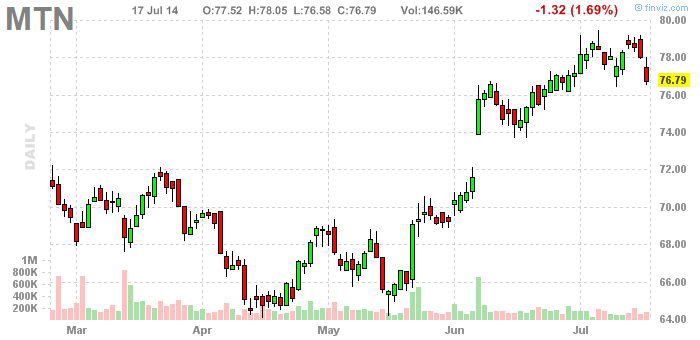
    As the market has not cooperated with my long breakout plays,  I want some exposure to the short side.  So why MTN?  After all it's been very strong since the middle of may. 

    Here's what I see.  Two new highs with declining MACD, that is typically suggestive of a topping pattern.  In addition earnings have already come out so I minimize my gap risk  

    Entry: $77.36.  Stop 79.50.  If the market stays under pressure I wouldn't put it past it for that 72 Gap to fill. 


    Wednesday, July 9, 2014

    A bit of a bounce. Stopped Out of GDXJ and some new action in Auto Parts. ORLY AZO

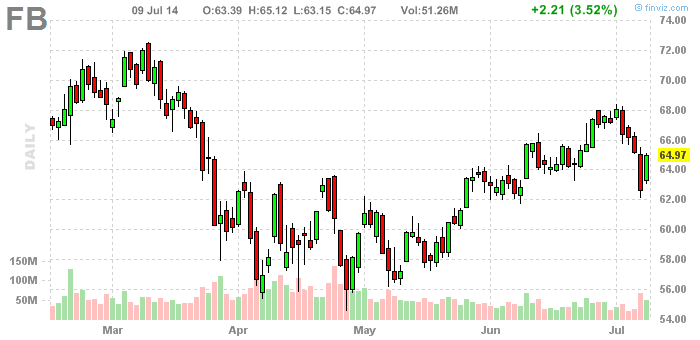
    After taking a beating over the last two days the markets staged a rally.  It looks like my FB trade was just a day early as FB rallied hard today:


    I thought 62 might act as support and it did. But I wasn't willing to move my stop to take the risk.  I guess you can't win them all.


    GDXJ has shown great strength and my short taken during the congestion must be closed.  
    Entry 40.76 closed 43.95. - 3.19.   I knew this was somewhat of a risky trade going into it as gold stocks are notorious for choppy actions and fake breakouts in both directions. So I positioned size accordingly. 1.5% loss here.

    Today's break was on high volume, which suggests I should look for long plays in some of the miners included in the ETF.


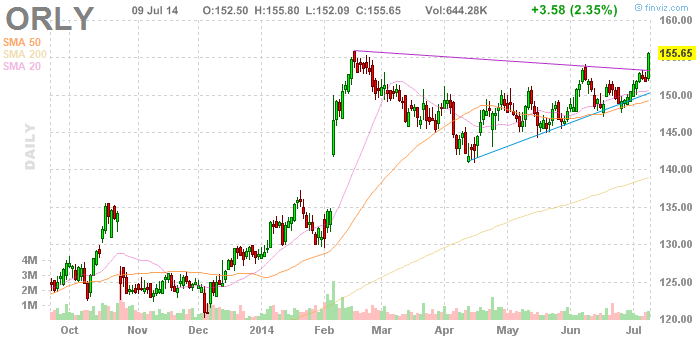
    New Positions:  In at 155.50.  A  very nice move out of congestion.  I'm playing this a smaller than normal so I have a stop at 151.90 . 

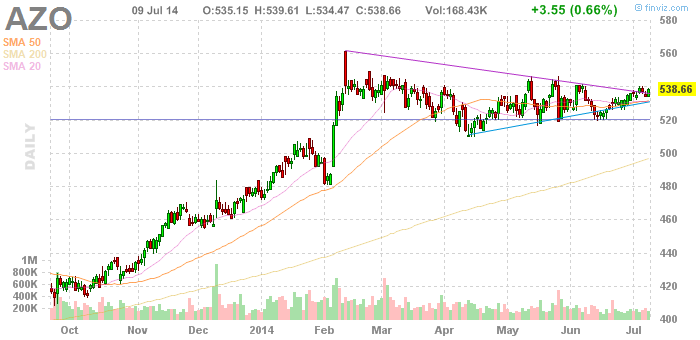
    Since ORLY broke out I'm anticipating that AZO will follow. So I picked up some calls:

    I picked up the July 550s calls.  This a high risk trade given the the option expo day. It either works tomorrow or I get out out because the Theta decay is going to get ugly real fast.

    On options my risk and position size is set assuming a  $0.00 so I'm risking .05%R here.


    What has me excited about both of these stocks is their monthly charts, A breakout on the weekly charts could produce some very big moves:

    ORLY weekly (dynamic):
    AZO (Dynamic )

    Thursday, June 26, 2014

    New position: Short GDXJ

    GDXJ was a stock (actually an etf of the junior minors) that got my year off to  a great start.
     Although that move failed, I got out with great profits.   It sank back down and has recently rallied.   This time I'm playing the fade.

    Short $40.76.   The news that sparked the rally was overblown in my opinion.  My sources tell me that it was short covering and that the smart money was selling into the rally.   I think it is likely that it will fade again.

    Stop @ 44 R. 1.5

    Monday, May 26, 2014

    YOD: Still nothing to see here.

    On Thursday, it was reported that Xeuchu He, a Chinese billionaire Picked up 2.2 million shares or so.  It was also reported that Shane Mcmahon picked up 24,600 shares.  I had no position when this happened but the market certainly liked the news and YOD closed up over 50% on huge volume.  

    The question I must ask is whether, does these events change my analysis and conclusion that YOD is fundamentally flawed.  I conclude that they do not and have re-entered my first tranche of my short.

    • The Shane McMahon Buy
    As I discussed in the context of my review of YOD's earnings this stock is being heavily diluted and sold by insiders.  1.3 Million shares were added so far this year.  

    Now Shane McMahon files an form F  announcing that Shane McMahon also bought 24,600.  shares on behalf of a trust Shane B. McMahon Trust u/a/ Vincent K. McMahon Irrev. Trust dtd. 12/23/2008, 24.  How is buy consistent with my conclusion that insiders are dumping?

     In filling out this form, McMahon had to list the number of securities owned following the transaction.  He lists 2,300,000


    Now let's compare that to what McMahon declared in the February 6, 2014 Form S3:

    C Media Limited (3) 9,142,8558,209,522933,333*
    Shane McMahon(4) 5,782,9852,829,0982,953,88718.0%


    The third column lists his shares following C-Media. 2.9 Million. In other words, he's cut his stake by 600K in just a few months. Heck, if you consider the shares he sold to C-Media (and I understand why he did as this company was out of cash and had received a delisting notice last August) He's cut his position by 40% in less than 6 months. 

     Second, I expect more selling from McMahon. I've noted that Shane McMahon has to exercise
     his warrants or he loses the right to do so and would make 4% interest. I base this conclusion on repeated statements in various filings, most recently the 10Q:


    "Effective on January 31, 2014, the Company and Mr. McMahon entered into Amendment No. 4 to the Note pursuant to which the Note will be, at Mr. McMahon’s option, payable on demand or convertible on demand into shares of Series E Preferred Stock of the Company (the “Series E Preferred Stock”) at a conversion price of $1.75, until December 31, 2014. " 


    The news that most people have been excited about is 2,285,715 share purchase by He. He purchased these shares from C-Media, which had recently purchased the shares from various insiders including McMahon.  The terms of the deal were not released.

    So is this a game changer? Or is YOD still the same company losing 89 Million since it engineered a reverse merger with a public shell company, Alpha Nutra (PINKSHEETSAPNAand became China Broadband in January 2007 (China Broadband changed its name to YOU on Demand in 2011.  (Don't you love "Chinese companies with American names) . YOD made  $138k in revenues last quarter.

    I am assuming that He purchased the shares at a discount. I base this assumption on the fact that most PIPE deals are discounted (sometimes significant) and also on the short period that C-Media has held their shares.Some have suggested that C-Media sold their shares after buying from the insiders to lock in He's experience and connections.  I admit that initially thought this scenario was plausible but after more research I do not believe that this was the reason C-Media sold to He for several reasons.

    First, Xeuchu He's fortune was made in mining. At Honbridge Holdings. Nothing in their organization chart would suggest a background, connections, or necessary experience in technology or video on demand, or even in China for that matter. He deals primarily with South American companies.

    To that end, I began researching the link between Xeuchu He and Xeusong Song (the head of C-Media).  The two had been associated on numerous "blank check" companies also known as Special Purpose Acquisition Companies ("SPACS")This is a process where He and Song, among other ("Jin Shi" a YOD board member) would create shell companies or engage in various reverse mergers.

    SPACS were big in the 1980s but were abused by insiders looking to make a fast buck through the promotion of the stock. The SEC then began placing more restrictions including the amount of money that must be raised and price of offering, etc.. , Surprise the SPAC is back in China. In any event, Song seems to have the experience and connections for all of these deals and does not need to buy He's experience. For all we know the shares could be a thank you gift from Song to He for investing in the other SPACS.

    Point being, I don't expect He to play a major role as an investor. He's not on the board, not part of management, doesn't have the authority to bind the company and does not have the background in the industry. And let's face 2.3 million shares of a $3 stock is not a whole lot of money to a billionaire to get actively involved.  By contrast he has his fortune tied up in Honbridge and his investors would probably not be pleased if he was avoiding his day job to work on a penny stock project.

    Regardless of He's involvement, (even if he took the CEO) is that I don't think YOD can compete against multi-billion dollar companies on the same content. 

    • YOD still offers nothing that Chinese Internet Giants do not already provide.
    YOD is going in to mobile now that its VOD cable has bombed. It is currently "pre-loaded" on one phone.  But guess what?  The mobile movie  market is already crowded with Billion Dollar Competitors:

    Yoku yoku mobile app
    LeTv http://mobile.letv.com
    Tenecent's QQ http://film.qq.com

    YOKU just missed earnings and got hit bad after guiding lower.  The reason more competition and increasing costs of content.  I thought the analyst's comments were very telling as they echo my sentiments on YOD:
    “They are in a dilemma,” Echo He, an analyst at Maxim Group LLC who has a sell rating on Youku, said in a phone interview. “If they spend money on content, they cannot make profit. If they don’t spend, there won’t be viewers and ads. They are in a tough spot.”
    Similar comments followed Tenecent's earning discussion on video.  So the big boys are all seeing compressed margins, the need to spend more on licensing and advertising to attract viewers. I don't see any possibility that YOD would be successful in such an arms race when it does not have the content, the infrastructure, or the money to advertise.  And the 138k in revenue demonstrate that it has not been successful.

    In conclusion, the YOD is still the same company with contracting revenue growth.   It's my opinion that day traders took the news and ran with it. Momentum always dries up without earnings. And as YOKU demonstrates revenue growth will become increasingly difficult in this sector.

    RISKING 1.5 R% on this one. 

    Friday, May 16, 2014

    CLOSED: GNRC

    Closed GNRC for a 5+ point move on the short side.  Average $ 57.29


    Reasons for entering the trade:
    The company makes generators and had what I felt would be inflated earnings due to adverse weather.  As the weather normalized, I expected earnings would normalize.   Sure enough 1st quarter they missed on revenue.

    Trade Assessment:
    This was not an easy one.  I used a stage entry,  but probably entered too early 56is. on the first of the position.   I allowed 2 R risk and when it dropped back under 60 I added @ 59 range.  My risk limit was nearly hit in March but fortunately it sold off.

    Exit:  Why did I close the trade?  Knowing when to get out on a profitable trade is the thing I find most difficult.  For a trade like my BAC trade, I had a long trend that could use a trend line as a stop. That's not present on a trade like this yet.  So after the first drop, I forced my self to stay in as it rallied back up to 55.  What I did not like, was seeing it reverse yesterday after hitting the 200MA.  It was acting much stronger than the broader market, so do I take the profits or the chance that the momentum fades and moving average support fails to hold?  

    Ultimately, I elected to take the profits.  I considered phasing out partially but I elected to put the money into other  opportunities.  If it continues to rally,  54 range, it might be worth trying to reinitiated a 1/3 position.

    Friday, May 9, 2014

    GNRC: Unraveling of the Sandy Premium

    I've been short GNRC (avg. $57.29)  on the premise that the generator company's earnings are temporarily inflated due to the horrible weather of the last year including Hurricane Sandy.  This was an IBD top momentum stock and had not been easy to hold 1st qtr.  Although it didn't push much higher it stayed strong... until first quarter earnings, which missed revenue. GNRC has pretty much acknowledged my theory to be correct and the stock falls.  I believe that there is more down side to go.  That being said, the gap is now closed and the 200MA might provide support. I may consider closing a portion of the position.


    Thursday, May 8, 2014

    YOD: Shorting the aftermath of a Pump and Dump for profit.

    April 6 , 2014
    $YOD trade diary.  I got short at 5.08 in A.H. after earnings.  They missed but it was bit up for a few minutes anyway.   It last closed at 4.09.  I believe there is more down side.

    On Friday there was news of a partnership with Miramax for mobile.  YOD traded as high as 4.99 premarket but sold off quickly opening at 4.50.  It was met by heavy selling that pushed it as low as 3.80.    It then preceded to churn most of the day.  I don't believe that support at the 4 will be able to hold.  Each time it dropped below it came from a great distance which I believe reflects exhausted seller.  Note that the volume was not heavy below 4.   I believe that it was a few stop orders that triggered .10-.20 drops after that level rather than being seen as a target for short selling.  Should there be a push below 4,  $3.80 is unlikely to hold and this could fall very fast. 

     I'm targeting $3.30, which is where it launched before the pump. The MACD showed very bearish divergence on the second push to $7.00.  This should have been the sign that this was finished  to the upside.  But the bearish MACD keeps getting stronger as the stock falls. 


    April 7
    More selling, 4 broke but it felt more like a slow grind rather than the sharp sell off type move


    I covered at 3.68, earlier than my profit target of 3.30 for several reasons.  First, the sell off was not very sharp today and was indicative of ambivalence more than panic.   Although I think it continues to go lower, there are better plays than waiting to squeeze every dollar out of this trade. Second, the overall market has been down pretty sharp.  There was some bounce movement in the momo players towards the end of the day, which could trigger a sharp uptick across the board.

    Overall 5.08 - 3.68 in a week.  For a $1.40 gain or 38%. That's a home run. 

    April 16, 2014

    I reconsidered my belief about the grind, and re-shorted. After trading to the 3.30 range.  YOD popped back up again to 3.70.  I again shorted it finally covering at 2.38

    Will it go lower?  Probably, but in the 2.30s I did not feel that it continues to make sense to hold the short position. It will probably be a slow grind to its death. But there are probably better uses of the funds than waiting for a 2.00 move, which may take 2 years.

    Wednesday, June 6, 2012

    NKE: Closed +$1.48

    I was stopped out of NKE at 107 today.   It went for a 1.48 gain, which is ok but I gave back 3 points of profit.  

    I have mixed feelings on this one,  Getting out with some profit is the right decision and the market is attempting to rally.  I still feel this has a much bigger move down so I probably was right in attempting to give this some room.

    Between this and WHR (both "winners"), I left a lot of money on the table.  My sell strategy needs work.